Pre-Winter Sale Limited Time 65% Discount Offer - Ends in 0d 00h 00m 00s - Coupon code: get65

CIMA Updated F1 Exam Questions and Answers by blake

Page: 11 / 18

CIMA F1 Exam Overview :

Exam Name: Financial Reporting
Exam Code: F1 Dumps
Vendor: CIMA Certification: CIMA Operational
Questions: 248 Q&A's Shared By: blake
Question 44

In 20X4, DEF closed its business having made a trading loss of $160,000. In DEF's country of residence, trading losses may be carried back three years on a LIFO basis.

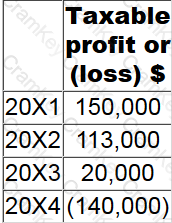
The profits for the last four years of trading were:
Questions 44

What are the taxable profits or losses for years 20X1 and 20X2?

Options:

A.

20X1 $10,000, 20X2 $113,000

B.

20X1 $143,000, 20X2 $ nil

C.

20X1 $150,000, 20X2 $133,000

D.

20X1 $150,000, 20X2 $nil

Discussion
Question 45

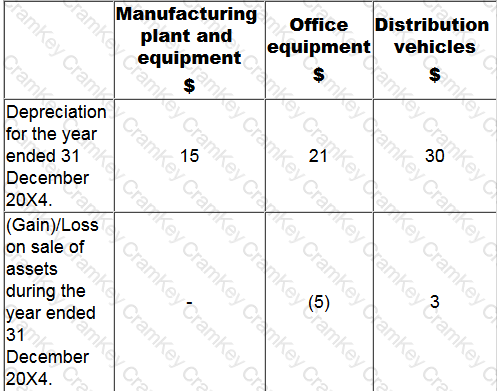
The following information relates to AA.

Extract of Trial Balance at 31 December 20X4;
Questions 45

Notes

(i) Inventory at 31 December 20X4 was valued at cost at $30.

(ii) The loan which was received on 1 July 20X4 is repayable in 20X9.

(iii) Corporate income tax represents an over-provision of tax for the year ended 31 December 20X3. AA reported a loss for tax purposes for the year ended 31 December 20X4 and a tax refund is expected amounting to $20.

(iv) Cost of sales, administration and distribution costs need to be adjusted for the following:

What figures should be entered on the face of the Statement of profit or Loss for the year ended 31 December 20X4 in relation to Interest and Corporate income tax?

Options:

A.

Interest $25 Corporate income tax $(37)

B.

Interest $25 Corporate income tax $37

C.

Interest $50 Corporate income tax $(3)

D.

Interest $50 Corporate income tax $3

Discussion
Question 46

Which of the following is NOT a primary need for regulating financial reporting information of incorporated entities?

Options:

A.

To improve the reliability of information for users.

B.

To make information more consistent.

C.

To make information more comparable.

D.

To ensure that information is consistent with its legal form.

Discussion
Faye
Yayyyy. I passed my exam. I think all students give these dumps a try.
Emmeline Sep 26, 2026
Definitely! I have no doubt new students will find them to be just as helpful as I did.
Ayesha
They are study materials that are designed to help students prepare for exams and certification tests. They are basically a collection of questions and answers that are likely to appear on the test.
Ayden Sep 14, 2026
That sounds interesting. Why are they useful? Planning this week, hopefully help me. Can you give me PDF if you have ?
Aliza
I used these dumps for my recent certification exam and I can say with certainty that they're absolutely valid dumps. The questions were very similar to what came up in the actual exam.
Jakub Sep 12, 2026
That's great to hear. I am going to try them soon.
Lennox
Something Special that they provide a comprehensive overview of the exam content. They cover all the important topics and concepts, so you can be confident that you are well-prepared for the test.
Aiza Sep 2, 2026
That makes sense. What makes Cramkey Dumps different from other study materials?
Conor
I recently used these dumps for my exam and I must say, I was impressed with their authentic material.
Yunus Sep 22, 2026
Exactly…….The information in the dumps is so authentic and up-to-date. Plus, the questions are very similar to what you'll see on the actual exam. I felt confident going into the exam because I had studied using Cramkey Dumps.
Question 47

Which of the following would be classified as a parent and subsidiary relationship in accordance with IFRS 10 Consolidated Financial Statements?

Options:

A.

Entity A owns 30% of another entity's equity shares and has the power to appoint or remove the majority of the members of the board of directors and control of the entity is through that board.

B.

Entity B owns 20% of another entity's equity shares and has an agreement with other equity shareholders of that entity that gives it power over a further 20% of the equity voting rights.

C.

Entity C owns 45% of another entity's equity shares and can exercise significant influence over that entity's financial and operating policy decisions.

D.

Entity D owns 25% of another entity's equity shares and associated voting rights and 100% of its preference shares.

Discussion
Page: 11 / 18

F1
PDF

$69.65  $199

F1 Testing Engine

$78.75  $225

F1 PDF + Testing Engine

$87.15  $249

